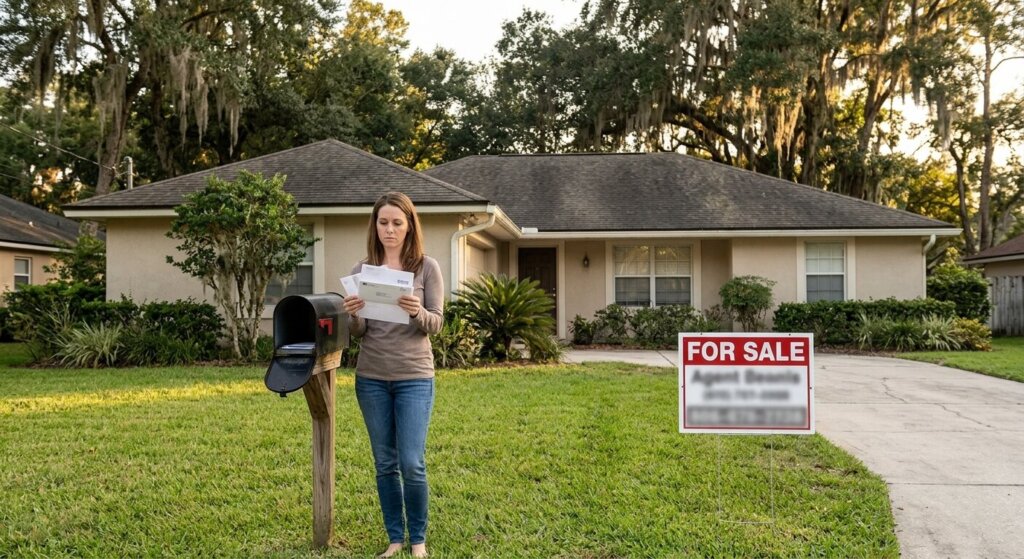
With property owners across Northeast Florida managing shifting economic challenges, understanding the home foreclosure process has never been more important. If you have recently missed a few mortgage payments or received an official letter from your bank, you might be asking yourself: What is a pre-foreclosure in Jacksonville, FL?
In simple terms, what is a pre-foreclosure comes down to understanding the initial legal period between the moment a homeowner falls behind on mortgage payments and the official date the bank reclaims the house at a judicial auction. When asking what is a pre-foreclosure, it is important to realize that this phase is not the end of your ownership, but a crucial warning window.
During pre-foreclosure, you still own your property. You retain the full legal right to live in the home, negotiate with your mortgage lender, or sell the house to pay off your debt in full.
Understanding what is a pre-foreclosure—and knowing your rights during this critical window—can mean the difference between losing your home to a court auction or walking away with your credit intact.
What Is a Pre-Foreclosure and How Does It Work in Northeast Florida?
When a homeowner misses 3 to 6 consecutive monthly payments, the lending institution issues a formal legal warning notifying the borrower to bring the account current or face foreclosure.
When examining what is a pre-foreclosure in our state, location matters significantly. Unlike states that use non-judicial deeds of trust, Florida is a judicial foreclosure state. This means your lender cannot simply repossess your home behind closed doors; they must file a formal lawsuit in the Duval, Clay, St. Johns, or Nassau County court system.
During a pre-foreclosure in Jacksonville:
- You are in a grace period: Banks do not want to own real estate. They prefer to work out a solution or receive payment in full.
- Your public record changes: Lenders will file a public document called a Lis Pendens (notice of pending lawsuit), alerting the public that legal action has commenced.
- You have legal options: Because the judicial court process takes time in Florida, you have an opportunity to take action before the bank schedules a final clerk sale.
The Florida Judicial Pre-Foreclosure Timeline: What to Expect in Duval County
To navigate pre-foreclosure successfully, it helps to understand the typical progression in local Florida courts:
- Missed Payments (Days 1–90): Late fees accumulate. The lender sends monthly default notices and hardship workout applications.
- Notice of Default / Acceleration Letter (Days 90–120): The bank officially demands that the full past-due balance be paid within 30 days.
- Lis Pendens & Summons (Days 120+): The lender’s attorneys file a court lawsuit in Duval County. You will be formally served with court papers and have 20 days to file an answer.
- Pre-Foreclosure Window: This is the critical 2- to 6-month window where you can negotiate a loan workout, list the home traditionally, or sell directly for cash.
- Final Judgment & Auction: If no resolution is reached, the judge signs a foreclosure judgment, and the property is scheduled for a public online auction by the Clerk of Courts.
4 Practical Options During Pre-Foreclosure in Jacksonville
If you are currently in pre-foreclosure, do not panic. You have four primary paths forward:
1. Refinance or Loan Modification with Your Lender
If your financial hardship was temporary and you now have steady income, contact your loan servicer immediately. You may qualify for a Loan Modification (re-amortizing past-due payments into your principal balance) or a Repayment Plan. If you have strong equity, a local mortgage broker might help you refinance into a lower monthly payment.
2. Request a Lender-Approved Short Sale
If you owe more on your mortgage than the home is currently worth in the Jacksonville market, you can ask your bank to accept a Short Sale. In a short sale, the lender agrees to let you sell the home for market value and absorb the remaining debt loss. While this will impact your credit score, it is generally far less damaging than a completed foreclosure judgment.
3. File for Bankruptcy Protection (The Option of Last Resort)
Filing for Chapter 13 bankruptcy triggers an “automatic stay,” immediately halting any scheduled foreclosure proceedings in court. While this buys you time to restructure your debt through a court-approved repayment plan, bankruptcy severely impacts your credit report for 7 to 10 years and should only be pursued after consulting a qualified Florida bankruptcy attorney.
4. Sell Your House As-Is to a Local Buyer like Buying Jacksonville Homes
If keeping the home is no longer feasible and you want to prevent a foreclosure judgment from destroying your credit score for 5 to 7 years, selling the home directly is often the fastest, most certain exit strategy.
At Buying Jacksonville Homes, we work directly with property owners facing pre-foreclosure:
- We Buy 100% As-Is: You don’t need to spend cash on repairs, deep cleaning, or fixing older Florida roofs.
- Fast Cash Closings: We can close in as few as 7 to 14 days—often fast enough to pay off the bank before a judicial sale date.
- No Agent Fees or Commissions: You pay $0 in real estate commissions or hidden closing fees.
Why Time Is Your Most Valuable Asset in Pre-Foreclosure
A completed foreclosure judgment can drop your credit score by 200 to 400 points and prevent you from securing a conventional mortgage, car loan, or even rental housing for 5 to 7 years.
The earlier you take action during pre-foreclosure, the more options you have:
| Action Path | Credit Impact | Out-of-Pocket Costs | Time Needed to Complete |
| Loan Modification | Minimal to Moderate | Low / None | 30 to 90 Days |
| Direct Cash Sale to Us | Minimal (Paid in Full) | $0 (Zero Costs) | 7 to 14 Days |
| Traditional Agent Listing | Minimal (Paid in Full) | High (6% Fees + Repairs) | 60 to 90+ Days |
| Full Court Foreclosure | Severe (200–400 pt drop) | High (Deficiency Judgments) | Determined by Court |
Frequently Asked Questions About Pre-Foreclosure in Jacksonville
Can I sell my home if I received a Lis Pendens in Duval County?
Yes. You retain full legal ownership of your home up until the moment the Clerk of Courts completes the final foreclosure auction. You have the legal right to sell your property and pay off the mortgage payoff balance at any point during pre-foreclosure.
What is the difference between pre-foreclosure and foreclosure?
Pre-foreclosure is the temporary grace period after you miss payments but before the bank takes ownership. Foreclosure is the completed legal process where the bank reclaims the property at a court auction and evicts the occupants.
Will selling my home in pre-foreclosure stop the lawsuit?
Yes. Once your sale closes at a licensed Florida title company, the mortgage payoff funds are wired directly to your lender. The bank’s attorneys will then file a formal motion to dismiss the court lawsuit and cancel the Lis Pendens.
Take Control of Your Pre-Foreclosure Timeline Today
When asking what is a pre-foreclosure, the most important takeaway is that you still have choices. You do not have to wait for the bank to dictate your financial future.
Whether you want to explore lender workout options, list your property, or receive a fast, no-obligation cash offer to pay off the bank entirely, our local team is here to help you evaluate your choices with empathy and complete privacy.
Call Buying Jacksonville Homes today at (904) 472-4914 or fill out our quick online offer form to discuss your pre-foreclosure options today!